
Dr. Paul Borosky, DBA, MBA
Business Plan Writer & Consultant
Colorado Business Plan Writer: Loans Light on Collateral
Along the Front Range, a healthy Colorado business can still be turned down because its equipment and building improvements are worth less than the loan it wants. The Colorado Housing and Finance Authority’s Cash Collateral Support program can cover that gap. It needs repayment numbers that hold up, and Dr. Paul’s plan supplies them.
Bank says collateral is short? Call or text (321) 948-9588. Dr. Paul answers personally.
Last Updated: 10/31/2026 · Written by Dr. Paul Borosky, DBA, MBA
Funding and Licensing Snapshot
Where a Colorado Loan File Gets Its Second Look
A short collateral position sends your plan to more desks. Here are the ones Colorado owners meet most.
SBA Colorado District Office
Colorado’s SBA district office covers owners in Grand Junction and Pueblo as much as in Denver. SBA lenders still underwrite the plan, guarantee or not.
CHFA Cash Collateral Support
The Office of Economic Development and International Trade (OEDIT) and the Colorado Economic Development Commission fund the program, and CHFA manages it. It deposits cash collateral behind a bank loan when the borrower’s own falls short.
Denver Economic Development & Opportunity
Denver’s economic development office makes small business loans for owners opening or growing inside the city. Read its rules before you pick a number.
Colorado SBDC Network
OEDIT hosts the lead center in Denver. Local centers run through community colleges, chambers and cities, including the Pikes Peak SBDC at the Catalyst Campus.
Colorado Secretary of State
Entities register with the Secretary of State and file a periodic report every year to stay in good standing. Miss it and a lender will notice.
Your City or County
Licensing runs through the city or county where you open, and the rules change by trade. Check the local wage rate at the same time, since Denver and Boulder set their own.
Let Clean Numbers Do the Heavy Lifting
When equipment and leasehold come up light, your numbers have to work harder. Pick how you want them built.
Business Consulting
For owners who run a solid shop and still hear no from the bank. Margins, cash timing and the records a lender trusts.
See consulting options →Business Plan Writing
FeaturedRepayment math a Colorado bank and CHFA can both test, laid out month by month, with the collateral picture told straight.
Start your plan →Business Plan Templates
Doing it yourself? Every template ships as a Word plan plus an Excel forecast for one industry. On the coffee shop template, you enter the Denver or Boulder wage rate on the payroll line.
Browse templates →Small Business Education
Lessons on comparing loans, finding break-even and paying yourself cost nothing to read. For the statements a lender leans on, Book 2 of the Fabled Forest Business School covers accounting and finance.
Start learning →City Spotlight
What Lenders Ask in Four Front Range Cities
A RiNo build-out, a Springs defense subcontractor, a Fort Collins laundromat and a Boulder lab startup all borrow differently. Each plan answers its own city’s question.
| City | What Drives Demand | The Plan Question |
|---|---|---|
| Denver | Union Station commuters, RiNo diners, Coors Field crowds, National Western Stock Show visitors | Should a Denver city loan come before the bank? |
| Colorado Springs | Fort Carson soldiers, Peterson and Schriever Space Force Bases, Space Symposium | How much backlog can one base hold? |
| Fort Collins | CSU students and staff, Canvas Stadium game days, year-round apartment renters | When to add attendant hours for move-in? |
| Boulder | CU Boulder, the NIST, NOAA and NCAR labs, Pearl Street visitors | Who buys besides the federal labs? |
Denver Economic Development & Opportunity makes small business loans to owners opening or growing in the city, from RiNo to Colfax Avenue.
“Should a RiNo business borrow from the city before a bank?”
The Plan FixBuild payroll on the Denver minimum wage rather than Colorado’s, and size the city loan request to the build-out alone. Then set break-even on weekday Union Station commuters, and treat Coors Field nights as upside rather than the base.
Fort Carson, Peterson and Schriever Space Force Bases and the Air Force Academy ring the Springs, and Space Symposium fills The Broadmoor each April.
“How should a Colorado Springs contractor spread work across Fort Carson and Space Force buyers?”
The Plan FixSplit the backlog among primes at Fort Carson, Peterson and Schriever, so no single base carries the business. Meet buyers at Space Symposium, then have the Pikes Peak SBDC at the Catalyst Campus check the mix.
Colorado State University move-in floods Campus West and College Avenue each August, and CSU football fills Canvas Stadium on fall Saturdays.
“When should a Fort Collins laundromat staff up for CSU move-in?”
The Plan FixAdd attendant hours for August move-in and sell wash-and-fold to Campus West renters by the semester. When CSU students leave for the summer, year-round apartment renters and standing wash-and-fold accounts carry the base.
NIST, NOAA and NCAR labs sit near CU Boulder, so Pearl Street lunch crowds and Gunbarrel startups both lean on research payrolls.
“Can a Gunbarrel lab-equipment startup sell beyond NIST and NOAA?”
The Plan FixName grant-funded buyers at CU Boulder and NCAR, then add private labs along the Diagonal. Budget every hire at the minimum wage the City of Boulder sets.
Customers and suppliers rarely stop at the border. See Dr. Paul’s pages for nearby Utah, New Mexico, Wyoming, and Nebraska.
From Dr. Paul’s Fabled Forest
When Collateral Comes Up Short, Let the Statements Talk
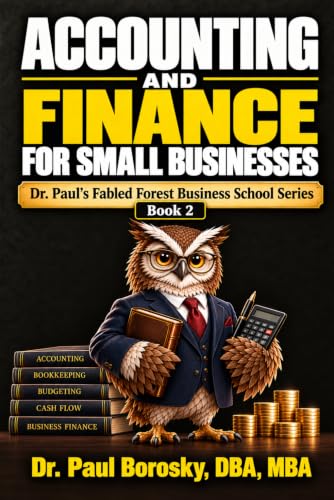
Dr. Paul’s Fabled Forest Business School · Book 2
Accounting and Finance for Small Businesses
When collateral falls short, Colorado lenders lean harder on statements and break-even math, which this book teaches in plain language. Lessons cover the income statement, the balance sheet and cash flow, so you can read your own numbers the way a credit officer does.
What will the lender look at when your equipment is worth less than you hoped? Your records. Let clean numbers carry the weight your assets cannot.
Doctor Owl, Dr. Paul’s Fabled Forest Business SchoolHow Dr. Paul Helps
How Dr. Paul Closes a Colorado Collateral Gap
A healthy business can still come up short on collateral. Your numbers must prove the loan works anyway.
- Cash Collateral Support packages. CHFA manages the program for owners whose equipment and leasehold fall short of the loan. Your bank attaches the plan to its request, so the repayment case has to stand on its own.
- Denver city loan requests. Denver Economic Development & Opportunity lends to owners opening or growing in the city. Your request is sized to the project, not padded.
- Statements that carry the file. Income statement, balance sheet and break-even laid out cleanly, because a lender leans on them harder when the assets are thin.
- Wages set city by city. Denver and the City of Boulder each set their own minimum wage. Every plan Dr. Paul writes uses the right one, and on the coffee shop template you enter your city’s rate on the payroll line.
- Seasonal businesses, planned honestly. Western Slope outfitters and mountain town shops get a forecast that shows how the busy season pays for the quiet one.
- No-cost coaching near you. Colorado SBDC Network centers run from Red Rocks Community College in Jefferson County to Front Range Community College in Larimer County, and Dr. Paul’s loan comparison guide helps you weigh offers.
Colorado owners often treat a collateral shortfall as a dead end. It is usually a cash flow question in disguise. When the equipment comes up light, the lender reads the projections twice as hard, so Dr. Paul builds them to answer that second read.
Real work in Colorado: Colorado owners have worked with Dr. Paul before. In 2022, he wrote an SBA-ready plan for a hair restoration clinic.
Learn It Yourself
Colorado Lessons on Numbers a Lender Trusts
When collateral is thin, the owner who knows the numbers cold gets the better hearing. These lessons get you there.
Watch
Two Front Range Tips From Denver and the Springs
One covers inventory math, the other covers the local economy. Both show up in a Colorado lender’s review.
Denver Tip #21: Project Your Inventory Levels in ExcelBuild an inventory forecast in a spreadsheet so purchases follow sales, not guesses.
Colorado Springs Tip #43: Economic Condition, Warm and SunnyHow to describe local economic conditions so a lender sees the market you are walking into.
FAQ
Colorado Owners Ask About Collateral, Seasons and Wages
How does CHFA decide whether a Colorado borrower qualifies for Cash Collateral Support?
Can a Western Slope outfitter with a summer-only season satisfy a Colorado bank?
Should a Boulder cafe budget payroll at the City of Boulder minimum or the state rate?
Dr. Paul Borosky, DBA, MBA
Business Plan Writer, Consultant & Author | 14+ Years | 1,000+ Clients Served
Dr. Paul Borosky, DBA, MBA is the founder of Quality Business Plan. He writes business plans and financial projections for owners across the United States and Canada, works remotely with clients in every state, and has written plans behind more than $100M in funded projects. He is the author of the Dr. Paul’s Fabled Forest Business School series and has published over 1,000 business videos on YouTube. He has taught as an adjunct college instructor and teaches in Florida public schools.
This page is for general educational purposes only. It is not legal, lending, or financial advice. Program rules, loan sizes and local requirements change, so confirm them with the program or agency before you apply. The Fabled Forest and its characters are fictional.