
Dr. Paul Borosky, DBA, MBA
Business Consultant & Author
Small Business Accounting and Finance: 20 Foundations Every Owner Should Know
Busy is not the same as profitable, and profitable is not the same as cash in the bank. Most owners learn that the hard way, on a Friday, with payroll due. These 20 foundations cover the score and how to use it, from bookkeeping and the income statement to cash flow, pricing, and break-even, in plain English.
Numbers keeping you up at night? Call or text (321) 948-9588. Dr. Paul answers personally.
Last Updated: 10/27/2026 · Written by Dr. Paul Borosky, DBA, MBA
The Short Answer
What Is Small Business Accounting and Finance?
Accounting is keeping the score. Finance is using it. Accounting records what happened to the money and reports it on pages you can read. Finance asks what those pages mean and decides what to do next. Most owners do a little of the first and none of the second. Both come down to four jobs.
Record
Write down every dollar in and out, in one place, with the business's money kept apart from yours.
- Separate accounts
- Bookkeeping
- Bank reconciliation
Report
Add it up into statements you can actually read, every month, before you make a decision.
- Income statement
- Balance sheet
- Margins and COGS
Analyze
Ask what the numbers mean: when cash runs short, what each sale leaves, and what an investment returns.
- Cash flow
- Contribution margin
- Break-even and ROI
Decide
Use the score to choose: what to charge, when to borrow, how much to hold back, and what next year looks like.
- Pricing
- Debt and financing
- Budgeting
You do not need to be an accountant. You need to know your score every month and use it before you decide. When the numbers live in one place and get read on a schedule, the business stops running on feel. That is the money side of Dr. Paul's Organize-Plan-Grow™ Strategy: organize the records, plan with them, then grow on purpose.
Every money fire I have seen started with a number nobody looked at. Every fix started with somebody finally looking.
Dr. Paul Borosky, DBA, MBA, Accounting and Finance for Small BusinessesThe 20 Foundations
Find the Number That Is Costing You
Each foundation opens with a question a real owner asks. Start with the one that sounds like you. The first ten are accounting: getting the money written down and added up. The second ten are finance: reading the numbers and acting on them. Stuck on a word? The accounting and finance glossary defines 66 terms in plain English.
Part One: Accounting, Keeping the Score
Foundations 1 to 10How to Separate Business and Personal Finances
"Are these my coins or the shop's coins? Does it matter?"Chapter 1 · One Pocket, Two Lives: A Monkey's Mix-Up
Separating business and personal finances means the business has its own bank account and its own records, and the owner gets paid through a set owner's draw on a set day.
Read the full guide →What Is Bookkeeping? A Simple System for Small Business
"Do I really need to keep every receipt?"Chapter 2 · The Shoebox Method: A Raccoon's Receipts
Bookkeeping is recording every dollar in and out of the business, in one place, in date order. A five-column ledger and one hour a week is enough to start.
Read the full guide →What Is a Chart of Accounts? A Sample for Small Business
"Where do I put the things that don't fit anywhere?"Chapter 3 · Everything Is Miscellaneous: An Octopus's Ledger
A chart of accounts is the short list of named categories every transaction goes into. If Miscellaneous is your biggest line, the list is not doing its job.
Read the full guide →What Is an Income Statement? How to Read a Profit and Loss
"I'm busy every night. Every night. Why don't I feel rich?"Chapter 4 · The Page He Never Turned: A Fox's Profit
An income statement, also called a profit and loss statement, shows what came in, what went out, and what was left for one period, usually a month.
Read the full guide →What Is a Balance Sheet? Assets, Liabilities, and Equity
"How can I be making money and still owe everybody?"Chapter 5 · Rich on Paper: A Labrador's Snapshot
A balance sheet shows what the business owns, what it owes, and what is left for the owner on a single day. Assets always equal liabilities plus owner's equity.
Read the full guide →How to Do a Bank Reconciliation, Step by Step
"Why does the bank say one number and our books say another?"Chapter 6 · Two Crabs, Two Totals: A Shell Game
A bank reconciliation matches your books to your bank statement line by line, sorting every difference into outstanding items, items not yet recorded, and true errors.
Read the full guide →How to Calculate Cost of Goods Sold (COGS) and Unit Cost
"Hypothetically. What does it cost to make one jar?"Chapter 7 · What Does a Jar Cost?: A Bee's Arithmetic
Cost of goods sold is what it costs to make or buy what you sell: materials, packaging, and the labor in each unit. Divide by units made to get unit cost.
Read the full guide →Gross Margin vs. Net Margin: How Overhead Eats Your Profit
"Why do my best sellers feel like they're losing money?"Chapter 8 · The Waffle That Lost Money: A Labrador's Margin
Gross margin is what sales leave after direct costs. Net margin is what is left after overhead too. A product can look great on the first and lose money on the second.
Read the full guide →How Much Should I Set Aside for Taxes? Small Business Tax Planning
"Why do taxes always surprise me?"Chapter 9 · Surprise, You Owe: A Horse's Autumn
Tax planning treats taxes as a known, scheduled cost. A share of income goes into a separate tax reserve every week, and estimated taxes get paid during the year.
Read the full guide →What Can a Small Business Write Off? Deductions and Recordkeeping
"What can I write off?"Chapter 10 · Best-Kept Secret, Best-Lost Receipt: A Squirrel's Sketchbook
A business deduction is a legitimate cost of running the business that lowers your taxable income, but only if your recordkeeping can prove it.
Read the full guide →Part Two: Finance, Using the Score
Foundations 11 to 20What Is Cash Flow? Why Profit Is Not Cash
"How can we sell out and still be broke?"Chapter 11 · Sold Out and Broke: A Fox's Busiest Month
Cash flow is when money actually moves in and out of the business. Profit says what you earned. Cash flow says what you have, and when.
Read the full guide →How to Get Customers to Pay on Time: Accounts Receivable
"How do I get people to pay on time?"Chapter 12 · Done Is Not Paid: An Ant's Unsent Invoices
Accounts receivable is money customers owe for work already done. Invoice the day the job ends, set clear payment terms, and follow up on a set schedule.
Read the full guide →How Much Cash Reserve Should a Small Business Have?
"How much should I keep in the bank, just in case?"Chapter 13 · One Bad Month: An Elephant's Rainy Day
A cash reserve is money kept in its own account to carry the business through a bad stretch. A common target is three months of the costs it takes to stay open.
Read the full guide →How to Price Your Product or Service: 3 Pricing Strategies
"How do I know what to charge for something I made?"Chapter 14 · Five Coins for a Month's Work: A Squirrel's Price Tag
A pricing strategy sets a price from three angles: your full cost, what the market pays, and what the work is worth to the buyer. Then it leaves room.
Read the full guide →What Is Contribution Margin? When to Discount Your Price
"Why am I losing jobs unless I'm the cheapest?"Chapter 15 · Winning Every Job, Losing Every Coin: A Raccoon's Bid
Contribution margin is what a sale leaves after its own variable costs. Know it before you discount, and set a minimum price you will not go under.
Read the full guide →How to Compare Business Loans: The True Cost of Financing
"Where can I get money fast?"Chapter 16 · Cash Now, Terms Later: A Monkey and a Shark
The cost of financing is everything you repay beyond what you actually receive: interest, fees, and terms. Compare loans on total cost, then check the payment fits.
Read the full guide →Good Debt vs. Bad Debt: Is Borrowing Ever a Good Idea?
"Is borrowing ever a good idea?"Chapter 17 · Measure Twice, Borrow Never: A Beaver's Loan
Leverage is using borrowed money to do more than your own money could. Good debt buys something measured to earn more than it costs. Bad debt does not.
Read the full guide →How to Calculate ROI for a Small Business Investment
"Why should I spend coins I have already saved?"Chapter 18 · Sitting on Coins: A Tortoise's Treasure
Return on investment compares what a spending decision brings back to what it cost. Opportunity cost is what you give up, including the cost of doing nothing.
Read the full guide →How to Calculate Your Break-Even Point Before You Buy
"How do I know if a new machine will pay for itself?"Chapter 19 · The Machine Before the Math: An Ant's Upgrade
Break-even analysis finds how many sales it takes to cover a cost: fixed cost divided by what each new sale leaves after its own costs. Run it before you sign.
Read the full guide →How to Create a Small Business Budget and Forecast
"How do I plan for a year I can't see yet?"Chapter 20 · Flying Blind: An Elephant's Year Ahead
A budget plans next year's money in and out, month by month. A forecast updates it as the year unfolds, with three scenarios and the actual beside the plan.
Read the full guide →Read Before You Buy
Read a Chapter: The Fox Who Sold Out and Went Broke
Fast Frankie finally reads his numbers. Then his best week ever leaves him short on payroll. If you have ever had a great month and an empty account, this one is for you. Here is how Chapter 11 begins.
Chapter 11 · Cash Flow
Sold Out and Broke: A Fox's Busiest Month
"How can we sell out and still be broke?"
The harvest festival ran for a week on the village green, Friday to Thursday, and by Tuesday the line at Fast Frankie's truck was still the longest one there.
Doctor Owl stood in it anyway. He had been told about the weekend by Mrs. Owl-Willow, by the newspaper, by Pedro, and by three separate creatures at the post office, and he wanted to see it for himself. It took twenty minutes. He did not mind. He spent them straightening the stack of paper napkins on the counter of the truck beside him, which belonged to a vole selling cider, and which the vole watched him do with growing respect.
The slice, when he got it, was excellent.
"Doc!" said Frankie, from the window, flour to the elbows. "You see this? Sold out Saturday. Sold out Sunday. Ran out of sauce at noon. Busiest weekend in the history of the forest. The paper said so."
"Congratulations," said Doctor Owl. "Mrs. Owl-Willow tells me Friday is payroll."
The window went quiet for a moment, which for Frankie's window was a long time.
"Marco talks too much," said Frankie.
"Marco talks exactly enough," said Doctor Owl. "Is it true?"
Frankie looked at the line, and then at the till under the counter, and then at Doctor Owl.
"Come by the restaurant Thursday night, when the festival's packed up. It's shut all week, we're all out here on the green," he said. "Two minutes! I've always got two minutes..." He stopped himself. "No. Thursday. As long as it takes."
It was the first time Doctor Owl had heard him offer more than two.
Frankie was at his desk in the back corner of the kitchen when Doctor Owl came in on Thursday evening, the festival over and the trucks parked. The restaurant was dark around them. He had Dex's page for the week in front of him, and the till's cash count beside it, and he had already put them side by side.
"Dex did the whole week," said Frankie. "Everything. The festival, the trucks, wages, all of it. Like you showed us." He pushed it across.
| Walk-up sales on the green | 140 |
| Three catering orders for festival parties (billed, paid in 30 days) | 120 |
| Revenue | 260 |
| Festival flour, sauce, cheese, boxes (paid cash at the market) | 80 |
| Space on the green | 30 |
| Wages for the week | 55 |
| Fuel, three trucks | 20 |
| New tire, truck two | 25 |
| Rent and lights, the week's share | 17 |
| Total expenses | 227 |
| Net profit for the week | 33 |
"Thirty-three coins of profit," said Frankie. "In one week. That's our best week ever. Twice a normal one." He pulled the cash count over. "And the till's got seventy-five in it. Friday I owe fifty-five in payroll and fifty-five to the supplier for last week's flour. A hundred and ten." He looked up. "I've never missed a payroll in my life. So which one's lying? The page or the till?"
"Neither," said Doctor Owl.
"One of them has to be."
"Neither of them is lying, Frankie. They are answering two different questions." He took a scroll from his coat, rolled it once, and unrolled it on the desk beside the page. "The page tells you what you earned. The till tells you what you have. Those are not the same question. They are almost never the same answer."
Thirty-three coins earned, thirty-five coins short. Where did the money go, and can Frankie make Friday's payroll? The rest of Chapter 11 is in the book.
Keep Reading on Amazon →The 60-Second Self-Check
Do You Know Your Numbers, or Just Your Bank Balance?
Four questions, one for each job. They come straight from line 2 of the Owner's Scorecard in the back of the book. Yes or no. No partial credit.
- Record
Does every dollar in or out get written down, in one place, at least once a week, with the business's money kept apart from mine?
- Report
Do I read an income statement every month, and could I tell you today what the business owns, what it owes, and what is left?
- Analyze
Do I know when my cash runs low in the next thirteen weeks, and what each job, product, or sale actually leaves after its own costs?
- Decide
Before I set a price, borrow, or buy equipment, do I add up the total cost and check it against a budget with a bad-year column?
Scored 3 to 5
Build the missing foundation yourself
Take your one "no," find its foundation in the 20 above, and work through that chapter and its Nutshell steps this month. Then score yourself again in 90 days.
Get the Book on Amazon →Scored 1 or 2
You need a CFO's eyes, not a full-time CFO.
When nobody is reading the numbers, the first fix is getting someone to read them with you. Dr. Paul works with owners as a part-time financial lead: cash flow, pricing, budgets, and the decisions in between. Call or text (321) 948-9588, or see fractional CFO services.
The Book
Accounting and Finance for Small Businesses
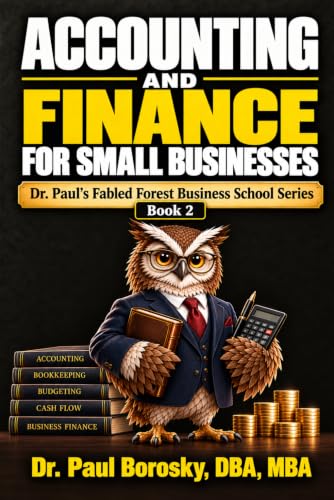
Book 2 of Dr. Paul's Fabled Forest Business School Series. The owners from Book 1 have their businesses running. Now they have to find out whether the businesses are working. Each chapter follows one of them through one money problem and teaches one real accounting or finance idea by its real name. Doctor Owl still asks before he answers. This time, he asks for the numbers.
- 20 chapters in two parts: accounting (keeping the score) and finance (using it)
- Dr. Paul's Nutshell after every chapter: what it is, why it matters, how to use it, and one question for you
- Doctor Owl's Wise Words and Mrs. Owl-Willow's Reminder: the lesson in one line, twice
- The Talon Way: seven money shortcuts that sound smart and cost more than they save
- A full glossary with every accounting and finance term defined
- Line 2 of the Owner's Scorecard, to pick the first fix and measure it in 90 days
Terms like accounts receivable, contribution margin, and working capital are taught by their textbook names and tied to a story you will remember at exam time. The numbers stay small on purpose, so the concept is the hard part, not the math. That makes the book a plain-English companion for intro accounting, finance, and small business courses. Want to practice on a real company? See how to read financial statements, using Apple’s 10-K. Teaching one and want to talk about using it? Call or text Dr. Paul at (321) 948-9588.
The Series
Ten Books, One Owner's Scorecard
Every book in Dr. Paul's Fabled Forest Business School Series adds one line to the Scorecard. Management came first so the business could run. Accounting and finance come second so you can tell whether it is working.
Want to go deeper on two of these foundations? Cash flow and budgeting each have their own full-length Fabled Forest finance book. See both on Dr. Paul's business books page. Ready for the owner’s whole money picture, from startup costs to the 13-week forecast? Read Small Business Finance for Beginners: What Your CFO Would Tell You.
FAQ
Common Questions About Small Business Accounting and Finance
What is the difference between accounting and finance?
What are the three main financial statements?
Why can a profitable business run out of cash?
What accounting should a small business owner do every month?
Who is Accounting and Finance for Small Businesses written for?
Do I need to be good at math to understand my business finances?
Learn the score with the book. Call when you want a second set of eyes on yours.
Dr. Paul Borosky, DBA, MBA
Business Consultant, Fractional CFO & Author | 14+ Years
Dr. Paul Borosky, DBA, MBA is a business consultant, author, and educator, and the founder of Quality Business Plan. He builds financial models, business plans, and budgets for small businesses across the United States and Canada, and serves as a part-time financial lead for owners who need a CFO's thinking without a full-time salary. He has written financial projections behind more than $100M in funded projects, is the author of numerous books on Amazon, and has published over 1,000 business videos on YouTube. He has taught as an adjunct college instructor and teaches in Florida public schools.
This page is for general educational purposes only. It is not legal, financial, tax, accounting, or lending advice. Tax rules change by place and by year, so talk with a qualified tax professional about your own situation. The Fabled Forest, its characters, and its businesses are fictional.