A Professional Business Plan Writer Who Builds the Numbers First
Most business plans fail at the bank for one reason. The words were written by one person and the numbers were pasted in by another, and the lender noticed. When you hire a professional business plan writer, you are not paying for writing. You are paying for a plan and a financial model that agree with each other and survive the loan committee. Dr. Paul Borosky, DBA, MBA has written more than 1,000 of them. He writes yours himself.
Or call/text (321) 948-9588. Dr. Paul answers personally.
Last Updated: 10/25/2026 · Reviewed by Dr. Paul Borosky, DBA, MBA
Four Ways to Hire Him
Most people land here needing a plan for a lender. Some already wrote one and need it fixed. Some need only the numbers. Some are open and need help running the business. Pick the one that fits.
Custom Plan Writing
The full plan and the financial model, written from scratch by Dr. Paul in 7 days or less. SBA, bank, investor, startup or expansion. Five plan sizes matched to your loan and headcount.
See plans and prices →Editing and Review
Already wrote your own? Dr. Paul reads it the way a lender will, fixes the structure, and tightens the financials so you are not declined on something that was easy to fix.
Send Dr. Paul your draft →Financial Projections
You have the narrative, or your lender only wants the numbers. The five-year model, break-even and loan schedule, built as a standalone from your real costs.
Projections only →Consulting and Fractional CFO
For owners already open. Pricing, cash flow, systems and growth, with Dr. Paul as a fractional CFO. Where people start when the business is busy but the money is not showing up.
Business consulting →Not sure which one? Call or text Dr. Paul at (321) 948-9588. He answers personally, and the first conversation is about your business, not a sales pitch.
What a Professional Business Plan Writer Actually Does
Here is the problem. Most owners think they are hiring a writer. Then the plan reads beautifully and the bank declines it anyway. The writing was never the hard part.
Here is what usually goes wrong. A nicely formatted document, a mission statement, a market section pulled from the internet, and a set of projections at the back that nobody can trace to a real cost. The lender flips straight to the numbers, cannot find where the revenue comes from, and stops reading. The plan looked finished. It was never built.
A professional business plan writer does three jobs. He structures the plan the way lenders actually read it. He builds and explains the financial projections instead of dumping numbers on a page. And he matches the plan to the loan it is walking into, because an SBA 7(a) for working capital, a 504 for a building, an equipment loan and an investor pitch are four different documents. Only the first of those three jobs is writing. If the person writing your plan cannot build your financial model, you have hired half a writer.
Three Mistakes Owners Make Writing Their Own Plan
Most plans get rejected for the same few reasons. Know them and you are already ahead.
No Proven Structure
Most owners write the plan as one long document with no clear order. A lender opens it, cannot find the summary, and loses interest fast. No structure means no roadmap, and a plan without a roadmap reads like a brain dump.
Dr. Paul Recommends: Use a two-part format. Lead with the executive summary, then the full plan behind it. The plan is really two plans in one. The reader gets the summary first. If they want more, it is right there.
Numbers With No Context
Most writers drop in a spreadsheet and walk away. Pages of figures, no explanation. The lender has to reverse-engineer what the numbers mean, and most will not bother. Numbers without a story raise more questions than they answer.
Dr. Paul Recommends: Walk the reader through them in order. Start with a projections highlight, then assumptions, then daily revenue, startup costs, and labor by month, then the profit and loss and income statement. Now the numbers tell a story.
Too Much Information
In the age of AI it is easy to write a mountain and say nothing. Forty pages of filler buries the three things a lender actually needs. More words do not mean more confidence. They mean more places to lose the reader.
Dr. Paul Recommends: Keep it simple. Address the topic, explain it, and stop. Just like eating cake, some is good but more is not better.
Entrepreneurs who write a formal business plan are 16% more likely to build a viable business than those who do not. Getting the plan right is not busywork. It moves the odds. Source: Harvard Business Review, Greene & Hopp, 2017
How Much Does a Professional Business Plan Writer Cost?
The market runs from under $200 to over $15,000 for the same words on the cover. Here is what you are actually buying at each level.
| Who | Freelance Marketplaces | Independent Professional Writers | National Firms |
|---|---|---|---|
| Typical price | $150 to $800Fiverr, Upwork and similar | $1,000 to $5,000One credentialed writer | $2,000 to $15,000+Quote only, rarely published |
| What you get | Usually a filled-in template. Market section from the internet. Projections, if any, typed into a table rather than built. | A custom narrative and a working Excel model, written from your costs and pricing by the person you spoke to. | A team. A salesperson, a writer, sometimes an analyst. Polished design. The writer is rarely the person on the sales call. |
| Timeline | 3 to 10 days | 1 to 3 weeks. Dr. Paul: 7 days or less. | 4 to 8 weeks |
| When the lender pushes back | Often no revisions, or a new order | Usually included for a defined period | Included, scheduled through the team |
| Right for | A class assignment, or a landlord who wants to see something | An owner going to an SBA lender or bank for $50,000 to $5 million | Institutional raises and companies with a budget line for it |
Four things move the price inside every one of those columns: the size of the loan, the page count the lender expects, whether the financial model is built or pasted, and how many revision rounds are included. Ask about all four before you compare two quotes. A $900 plan with no model and a $2,500 plan with one are not the same product at different prices. They are different products.
A mid-range professional plan at $1,500 on a $350,000 SBA loan costs less than half of one percent of the money it is asking for. The plan is the cheapest line in the deal. The expensive version is the one that gets declined and costs you the six months. Illustration using market-range pricing. Your loan size and plan price will differ.
Dr. Paul publishes his prices, which most writers do not. See the plans and prices here, then come back and finish reading if you want to know how to judge a writer.
Is There Such a Thing as a Certified Business Plan Writer?
No. And you should be suspicious of anyone who says otherwise.
There is no licensing body, no state registration, no exam and no professional board for business plan writers. Nothing like the CPA for accountants or the bar for attorneys exists. When a website says "certified business plan writer," the certification was either issued by the writer to himself or purchased from a company that sells certificates. Neither tells you whether the plan will get funded.
So judge on what can be verified instead. Graduate credentials in business or finance, which you can look up. The number of plans written, which should be a specific figure. Whether the writer builds the financial model personally or hands it off. And whether plans they wrote have actually been funded, in dollars. Dr. Paul holds a Doctor of Business Administration and an MBA in Finance, has written more than 1,000 business plans over 14 years, builds every model himself, and his plans have supported more than $100 million in funded projects. None of that is a certificate. All of it is checkable.
Nobody certifies business plan writers. The bank does, one loan at a time. Ask how many of theirs have been funded, and in what dollar amount.
Dr. Paul Borosky, DBA, MBASeven Questions to Ask Before You Hire a Business Plan Writer
Ask these of anyone you are considering, Dr. Paul included. The answers sort the field fast.
Who actually writes it?
Ask for a name. If the answer is "our team," the person you are talking to is in sales. Dr. Paul writes every plan himself and takes the intake call personally.
Do you build the financial model, or paste one?
Ask to see a model from a past plan with the client's name removed. A built model has assumptions you can change and watch flow through. A pasted one is a picture of a table.
Have your plans been funded by SBA lenders?
Ask for a dollar figure, not a yes. Dr. Paul's plans have supported more than $100 million in funded projects across 14 years.
What happens when the lender asks for changes?
They will. Ask whether revisions are included, for how long, and who does them. A writer who charges a new fee for the lender's first round of notes is not finished when they say they are.
What do you need from me?
The right answer is a list: your costs, your pricing, your loan amount, your lender's requirements, your resume. A writer who needs nothing from you is going to make it up.
How long, and what starts the clock?
Dr. Paul delivers in 7 days or less from the point he has your numbers. Any writer who promises a date without asking when they will have your information is guessing.
What is not included?
Pitch deck, grant narrative, investor memo, a second plan for a different lender. Know what is extra before you sign, so a $1,200 plan does not quietly become a $3,000 one.
If a writer gets uncomfortable with question two, you have your answer.
What Lenders Actually Look For in a Business Plan
Almost every owner who hires a professional business plan writer is doing it because a lender asked. So write for the lender. Here is what the underwriter flips to, in roughly this order.
Use of funds comes first because the lender wants to know you are not borrowing for working capital and buying a truck. Debt service coverage comes second because it is the one number that decides whether the business can pay them back. Owner injection comes third because a borrower with nothing in the deal is a borrower who can walk. And then the assumptions page, because every projection is only as good as the sentence that explains where the revenue comes from.
Debt service coverage, worked out
Say the loan is $350,000 on an SBA 7(a) at roughly 9.5 percent over 10 years. The payment is about $4,530 a month, so about $54,350 a year. A lender wanting 1.25 times coverage needs to see the business generate about $68,000 a year in cash available for debt service, after the owner is paid a real salary.
That $68,000 is the number the whole plan has to prove. Not claim in the executive summary. Prove in the model, from units sold, prices charged and costs quoted. A plan that gets to $68,000 by typing it into the cell gets declined. A plan that builds to $68,000 from the ground up gets a second meeting. Dr. Paul builds the model first for exactly this reason. See the SBA's own 7(a) overview for the program basics, and how the projections are built if you want the detail.
Local Lenders Read Plans Differently
Banks are only part of the picture. City loan funds, state programs and nonprofit lenders each want something a little different, and Dr. Paul has written plans for all of them. Five examples, each built around a real plan:
- Pittsburgh: the city lender's startup loan packet, and a $526,000 wellness center plan.
- St. Louis: buying a business with seller financing and a bank loan.
- Nashville: one expansion plan written for a lender and a visa reviewer.
- El Paso: funding a new contract without running out of cash.
- Savannah: a day spa plan built on a low-cost pricing strategy.
See What a Real Business Plan Looks Like
Before you hire anyone, watch Dr. Paul walk through a real, professionally written plan, section by section. This is the document you are paying for.
Basic Business Plan Example by Dr. Paul Borosky, DBA, MBA. A 7-minute look at every section of a real business plan: cover page, executive summary, market analysis, and financials, so you know exactly what to expect.
Every Section of a Business Plan, in Order
A fundable plan builds the story first, then proves it with numbers. Here is every section Dr. Paul includes, in the order a lender reads them. A shorter plan for a small loan carries the same sections with less depth. A full lender plan for an SBA loan carries all twelve at full depth, plus a sensitivity case.
Executive Summary
The whole plan on one page. Written last, read first. If a lender reads only one thing, it is this.
Company Description
Who you are, what you do, and why the business exists. The short version of your story.
Products and Services
What you sell, how it works, and why people pay for it.
Target Market
Who your buyers are, how many of them there are, and what they need from you.
Location
Where you operate and why that spot works for the business, from foot traffic to logistics.
Industry Research
The market around you. Its size, its trends, and where your business fits.
SWOT Analysis
Strengths, weaknesses, opportunities, and threats. An honest look at where you stand.
Funding Request
How much you need, what it buys, and how the money gets used. Clear and specific.
Financial Assumptions
The logic behind the numbers, stated openly so a lender can follow your math.
12-Month P&L
Profit and loss month by month for year one. Where the plan meets reality.
5-Year Income Statement
Revenue, costs, and profit projected out five years. The long view.
5-Year Balance Sheet
Assets, liabilities, and equity over five years. The financial backbone of the plan.
Every plan ships with its Excel model, and the model stays yours. Want the full walk-through? See how a professional business plan is built.
Roughly 38% of startups fail because they run out of cash or cannot raise new capital, the single most common reason in CB Insights' review of startup post-mortems. Honest financial projections are how you see the crunch coming. Source: CB Insights, Why Startups Fail
From Deposit to Lender-Ready in 7 Days or Less
The process runs on Dr. Paul's Organize-Plan-Grow™ Strategy, the same framework behind every client engagement. Three phases, and you talk to the same person in all three.
Organize
You pick your plan on the prices page and Dr. Paul calls. One intake conversation to get the business, the loan and the lender's requirements straight. He needs your costs, your pricing, your loan amount, your lender's checklist if you have one, and your resume.
Plan
The model gets built first, from your numbers. Then the narrative is written to match it, section by section, executive summary last, so the words and the projections tell one story. Then a review call to walk the draft.
Grow
Revisions from the review call, final files in Word and Excel, and the plan goes to your lender. When the lender comes back with notes, you send them to Dr. Paul. The model stays yours to update as the business changes.
Ready to start? Pick the plan size that matches your loan and Dr. Paul will call you. Or call him first at (321) 948-9588.
Businesses that plan grow faster. Research from the University of Warwick found that companies which write a formal business plan grow around 30% faster than those that do not. Planning is not paperwork. It is fuel for growth. Source: Burke, Fraser & Greene, University of Warwick, Journal of Management Studies
Who Dr. Paul Writes Business Plans For
Around 30 industries, all 50 states and Canada, and a dedicated page for the cities he serves. A few of the industries with their own full guides:
Intake is by phone or video and files move by email, so where you are rarely matters. What matters is that the writer knows your industry's numbers. A restaurant plan that does not know food cost, or a trucking plan that does not know cost per mile, gets found out on page two.
Before You Hire a Business Plan Writer, Read These
The questions people ask Dr. Paul before they hire him, each answered in full on its own page.
Business Plan Writing Questions
The ones Dr. Paul hears on almost every first call.
How much does a professional business plan writer cost?
It depends on who is writing it. Freelance marketplaces run roughly $150 to $800 and usually deliver a filled-in template with no financial model. Independent professional writers run about $1,000 to $5,000 for a custom plan with a working model. National firms run $2,000 to $15,000 and up, by quote, with a team and a longer timeline. Dr. Paul publishes his prices on the prices page so you can compare before you call.
How long does it take to write a business plan?
Most plans carry a 7-day delivery guarantee. Got a hard deadline, like a lender meeting or an SBA submission? Tell Dr. Paul up front. He has worked off-hours to hit a client deadline more than once. Start with a quick call about your timeline.
Do you write SBA business plans?
Yes. Dr. Paul has written SBA-ready plans for 1,000+ clients, supporting $100M+ in fundable projects. Every plan includes financial projections, assumptions, and the structure lenders actually follow. Not just numbers dropped on a page with no context.
How should financial projections be presented?
Walked through, not dumped in. Dr. Paul leads with a projections highlight, then assumptions, then daily revenue, startup costs, and labor by month. Only then comes the profit and loss for 12 to 24 months and the income statement. By the time a lender hits the numbers, they already understand them.
Who actually writes my plan?
Dr. Paul Borosky, DBA, MBA. Not a junior writer, not a contractor, not software. You talk to him on the intake call, he writes the plan and builds the model, and he is the one who walks you through it. Ask any firm you are comparing the same question and listen for how long the answer takes.
What happens if my lender asks for changes?
You send Dr. Paul the lender's notes and he makes the changes. Lenders ask for a different loan structure, a revised use of funds, or a sensitivity case more often than people expect, and a plan built on a working model can absorb that in hours, not weeks. Ask about revision terms before you start, with any writer.
Can you edit a plan I already wrote?
Of course. Send it over. Dr. Paul reviews the structure, checks the financials and assumptions, and tells you straight what it needs to be lender-ready. That way you do not get rejected on something that was easy to fix.
Is there a certified business plan writer designation?
No. There is no licensing body, exam or state registration for business plan writers, so the word certified on a writer's website means whatever that writer decided it means. Judge a writer on verifiable things instead: graduate credentials, how many plans they have written, whether they build the financial model themselves, and whether their plans have been funded.
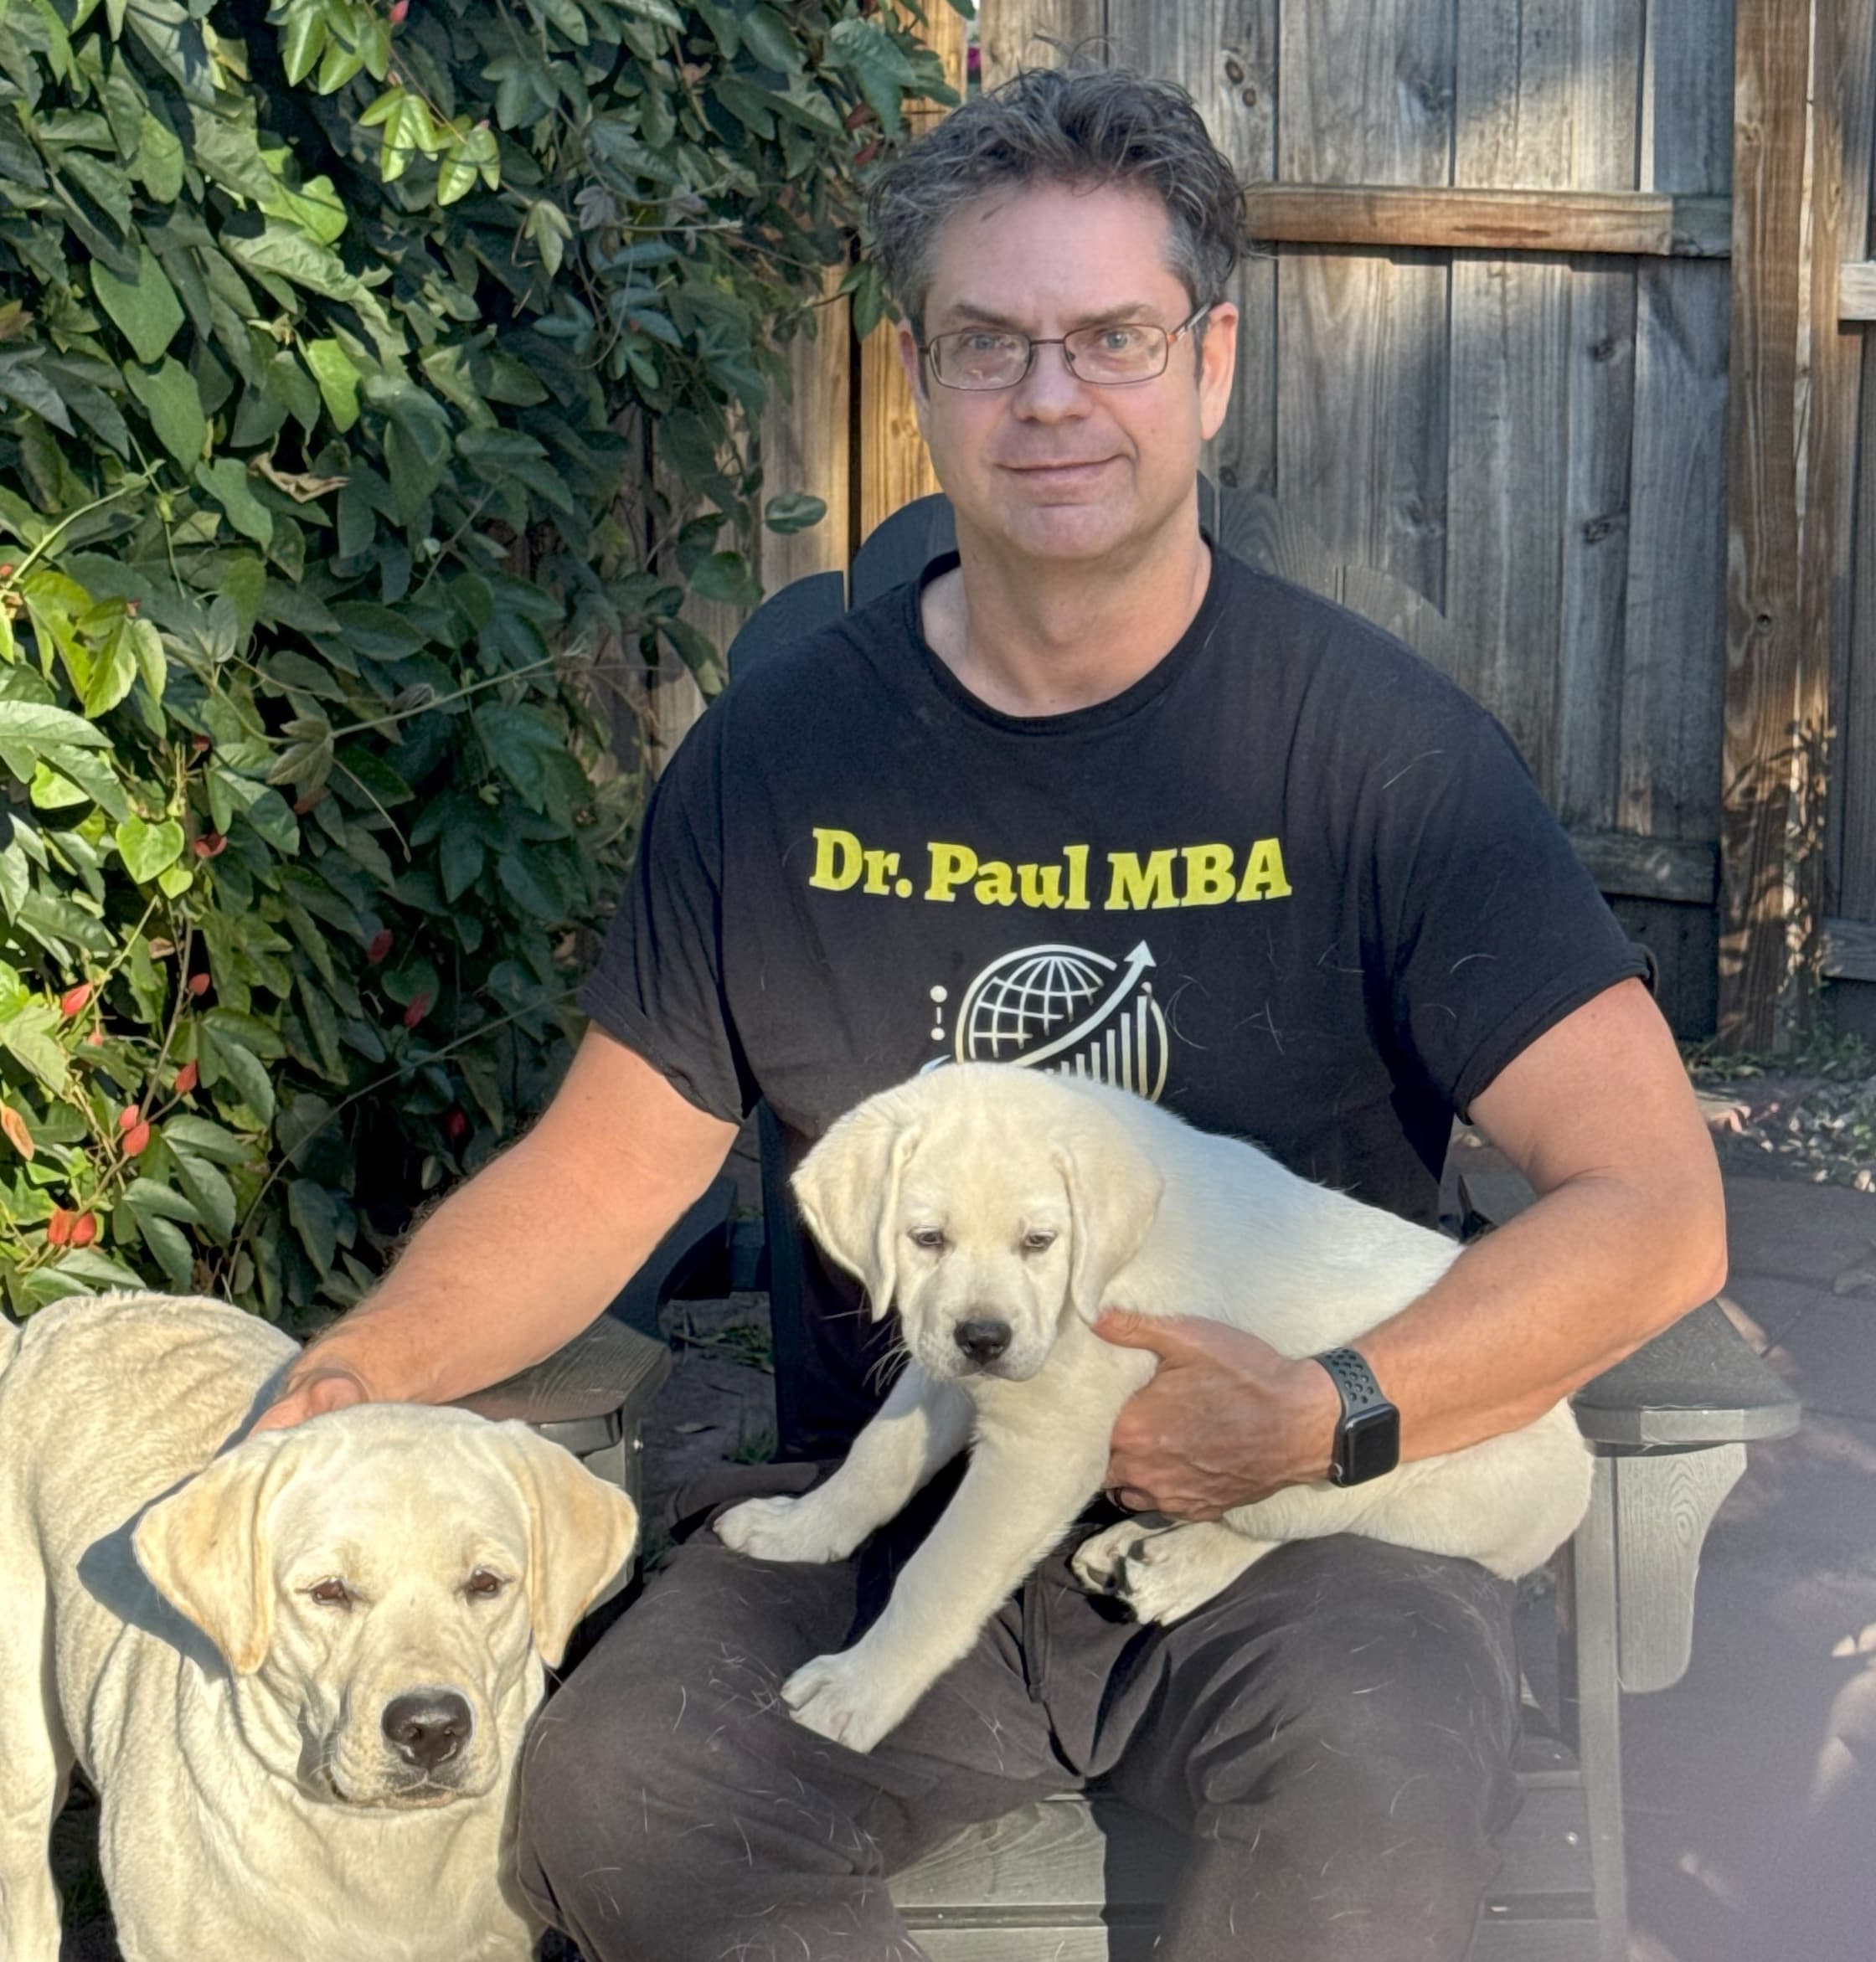
Dr. Paul Borosky, DBA, MBA
Dr. Paul Borosky holds a DBA from National University and an MBA with a focus in Finance from Webster University. For 14+ years he has helped 1,000+ owners turn ideas into funded businesses. He is the founder of Quality Business Plan, creator of the Organize-Plan-Grow™ Strategy, author of more than 25 books on small business finance and planning, and publisher of over 1,000 business videos on YouTube. He writes every professional business plan personally, builds every financial model himself, and answers his own phone.
Why Hire a Professional Business Plan Writer
Your plan is often the only version of your business a lender ever sees. A professional business plan writer makes sure it is structured, backed by a model that holds up, and easy to say yes to. When you are ready, Dr. Paul writes it, edits yours, or builds the numbers. No pressure, just a conversation.
See Plans and Prices